What is volatility trading?
Volatility trading entails gambling on an underlying instrument’s expected future volatility.
The purpose of a volatility trading strategy is to estimate the amount by which the stock price will vary irrespective of current trends and price action, rather than trading directly on the stock price (or futures) and trying to predict market direction.
Volatility is an essential part in the options pricing mechanism. Risk and reward are also highly correlated with volatility.
The option price is made up of six different elements:
- Fundamental cost.
- The striking price
- Duration till expiration
- Interest Rates
- Payouts: Unpredictability
- Implied volatility (IV) is a technical term for volatility trading.
For example, if Amazon stock, which is now trading at $2,000 per share, has an implied volatility of 20%, the range for the next year is $400, or one standard deviation. In other words, AMZN’s stock price is expected to range between $1,600 and $2,400 during the next year.
The idea of leveraging volatility in trading intrigues many people. You will learn how to apply these approaches to increase your expected return on investment.
We have you covered, as you can see below: Volatility Trading Strategies: Earn Money Without Predicting Price Direction.
How Do You Trade Volatility?
To understand how to leverage volatility in trading, think of options as an insurance policy. All types of insurance, including life, car, and property, act as a hedge against the chance of future financial losses.
Applying this concept to stock options suggests that in an uncertain market, traders would buy more option contracts. The option price will climb when additional demand enters the market.
Furthermore, the following describes how volatility is affected:
- Implied volatility (IV) increases in line with rising option prices.
- Implied volatility (IV contraction) decreases as option prices decline.
Note: We can assess if it is a good time to sell or buy options by looking at the implied volatility.
Perhaps it’s time for a change if your method relies mostly on generating market forecasts and you’re still struggling with it. The most typical novice blunder is continuing to trade even when it is impossible to foresee future market developments.
To win this struggle, you must trade volatility, not price.
Volatility Trading Strategies
Trading in volatile markets may be done safely by using options and volatility trading strategies.
Do you want to be as knowledgeable about trading as the professionals?
Afterward, we will cover three volatility trading strategies with you that have the potential to deliver significant profits:
- Using IV to predict stock prices
- Historical versus applied Volatility Strategy
- Diagonal Spread strategy for Long Calls
Remember that there may be risks connected with trading volatility. Developing a successful trading risk management strategy will be critical. Without a sound trading strategy, you run the danger of losing all of your money rapidly.
Our skilled staff at Trading Strategy Guides constantly encourages responsible trading and suitable risk management. Remember that keeping an eye on your beta and alpha risk exposure is what makes your volatility trading strategy effective.
Using IV to predict stock prices
Let’s take a look at an example situation to see how we may use implied volatility to help us decide which volatile trading strategies to apply.
Trader Joe aims to profit on the ABC stock’s bearish trajectory.
Our trader Joe may now profit from bearish trends by adopting two traditional bearish options strategies:
- Purchase a put option.
- Selling a call option.
The optimal option contract may be calculated using implied volatility.
To do this, let’s look at how call and put options work.
To begin, the negative Vega component of implied volatility may benefit call strategies by reducing implied volatility. However, the fundamental asset must trade below the call strike. We prefer that there be no tradeable value upon expiry.
However, rising implied volatility makes buying-put methods more appealing. The positive component of Vega is the cause of this. Put options must grow in value in order to generate a profit.
So, which of the two volatility trading strategies is more effective?
Inferred volatility influences the reaction.
Here’s a trading tip for options.
Rather than studying ABC’s implied volatility, we should focus on the IV’s trading position relative to its own volatility range.
Because the IV for ABC stock is trading toward the bottom of its range, we will make this assumption.
The implied volatility graph is shown below:
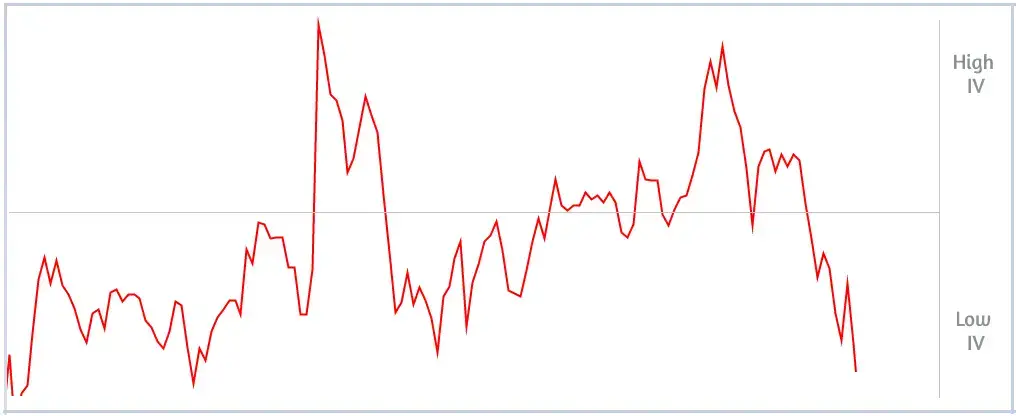
Implied volatility is more likely to rise than fall from this point forward.
Can you now tell which of the two volatility options strategies will benefit the most from an increase in implied volatility?
In this case, more volatile markets would be good for the “Buying Put Options” strategy.
You can also read: 3 Tips For A Massive Profit In Stock Market Index Trading
Note that the real stock price typically falls as implied volatility rises. This confirms our gloomy forecast.
Historical versus applied Volatility Strategy
One of the most common volatility trading strategies is to use the difference between implied and historical volatility.
Implied volatility is easily understood when compared to historical volatility. The second is based on historical data, while the first is based on current data.
Consider how insurance companies overestimate the possibility that your house may burn down. When trading volatile stocks, the same overestimation principle applies; therefore, options will always exaggerate implied volatility.
We are trading volatility early in the expiration cycle by selling heavily overpriced implied volatility. We do this with the understanding that, as we approach expiration, the majority of our option transactions will experience higher value decay than the underlying instrument.
This suggests that our potential profit is equal to the difference between the option price and the underlying stock price.
Historical volatility refers to experienced volatility across time, while implied volatility seeks to forecast future stock price ranges. In other words, past volatility reflects the stock price’s genuine volatility. This paper trading options tutorial will let you compare your projections to the market.
The two main contrasts between implied and historical volatility are as follows:
- One seeks to foretell what will happen in the future, while the other illustrates what has actually occurred.
- The IV is based on option pricing (calls and puts), while historical volatility is based on the current price.
In summary,
Offering options with high implied volatility may give you a competitive edge.
Consider the following example: we compare the monthly implied volatility to the realized volatility chart of a randomly picked business.
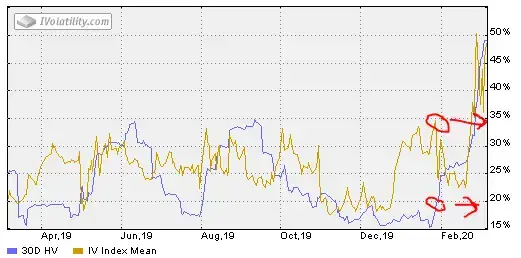
Despite their link, these volatilities vary somewhat, as shown. There are times when the implied volatility is greater than the historical volatility. As of right now, the market was forecasting 35% implied volatility.
Following that, we look at the expiration date to check whether the market has changed by 35 percent or more (less).
Tired of losing trades? Open a Libertex account to start trading stocks and forex with the professionals today.
Interestingly, the blue line indicates historical volatility, while the yellow line reflects implied volatility.
When we compare the IV to historical volatility, we can see that the market only changed by 20% during that period.
In general, implied volatility surpassed actual volatility. We should also consider the rare cases in which the market moved faster than expected.
Because the market expects volatility to always be higher, yet real volatility is lower than expected, we have an edge as options traders.
Diagonal Spread strategy for Long Calls
This kind of volatility trading strategy works well with range-bound underlying products.
Ranging markets may allow us to focus more on the influence of implied volatility on stock prices.
Some traders are intrigued about the functioning of the long call diagonal. This particular diagonal often prompts traders to start or cancel a new position.
A long call diagonal employs two distinct types of spreads:
- The opportunity to sell out of the money (OTM).
- Buying the in-the-money (ITM) option.
Although the expiration cycles differ, both options have the same strike price. The money options have an extra date for expiration.
In conclusion
Finally, while trading volatility, you might choose to remove yourself from market swings. It also helps you create more accurate and flexible transactions.
Volatility trading approaches seek trading opportunities that extend beyond price movements. Understanding implied volatility and volatility trading will help you choose the best option strategy.
A quick overview of what you’ve learned is as follows:
- There are three strategies for trading volatility: price, VIX, and options.
- It allows you to profit without having to guess where prices will go.
- Implied volatility represents the projected future volatility.
- The movement of implied volatility and option prices is concurrent.
- Selling excessively priced IV options may provide you with an advantage since implied volatility exceeds anticipated volatility.
Thanks for reading! Follow for the latest news and information Telegram Channel